

Blogs
PW Consulting Projects Pharma Track and Trace Market to Hit $344.8M by 2032 with 12.5% CAGR
By PW Consulting, 2026-09-16
Navigating the New Era of Pharmaceutical Traceability: Strategic Insights for 2026 Decision-Makers
The global pharmaceutical landscape is undergoing a structural transformation driven by stricter regulatory mandates, supply chain complexity, and an urgent demand for product integrity. As governments worldwide tighten track and trace requirements, the infrastructure supporting serialization, aggregation, and compliance verification has evolved from a back-office compliance function into a core strategic asset. PW Consulting's latest Pharma Track and Trace Solutions Market research report maps this evolution with granular precision, offering executives and investors the analytical framework needed to navigate the forecast period from 2026 through 2032.
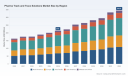
For corporate strategists, procurement leaders, and investment committees, the stakes could not be higher. The market has demonstrated consistent momentum over the past half-decade, with overall revenue scaling from approximately $163.15 million in 2020 to $215.0 million in 2025. The forecast trajectory projects continued expansion, reaching an estimated $344.8 million by 2032, underpinned by a compound annual growth rate of 12.5 percent. These figures are not abstract metrics; they reflect the compounding pressure of interoperability mandates, the shift from fragmented point solutions to integrated platforms, and the rising cost of non-compliance across regulated jurisdictions. This article serves as a strategic preview of our comprehensive market intelligence, highlighting why mastering these dynamics is essential for 2026 planning cycles.
Pharma Track and Trace Solutions Market
Why 2026 Is the Defining Inflection Point
The 2026-2032 forecast window captured in our report is not merely a spreadsheet exercise. It aligns directly with a cascade of regulatory deadlines that are reshaping procurement priorities, technology roadmaps, and partner selection criteria worldwide. Organizations planning capital allocation, vendor consolidation, or manufacturing line upgrades in 2026 must account for the fact that compliance is no longer a single-market checkbox. It is a multi-jurisdictional, multi-layer operational requirement that touches serialization, aggregation, data exchange, and downstream verification in a single integrated workflow.
Convergence of Major Regulatory Frameworks
Our research details how three dominant regulatory architectures are simultaneously forcing investment in end-to-end traceability capabilities. In the United States, the Drug Supply Chain Security Act continues its phased push toward full electronic interoperable package-level tracing and verification. Enforcement milestones have already activated obligations for manufacturers and repackagers, while larger dispensers face their own compliance timelines. Notably, targeted stabilization measures and extension pathways have been granted to smaller dispensers to support a more orderly industry rollout. The practical implication for 2026 is clear: trading partners that have deferred system integration or data standardization are now confronting operational risk, supply disruption exposure, and potential enforcement consequences.
Across Europe, the Falsified Medicines Directive and the European Medicines Verification System have driven widespread adoption of unique identifier uploads and pharmacy-level verification of safety features. With full compliance largely established across most EU member states by 2025, the operational focus in 2026 has shifted from baseline adoption to system optimization, exception handling, and alignment with broader supply chain digitalization initiatives.
Perhaps the most dynamic developments are unfolding in emerging regulatory markets. In Egypt, the Egyptian Drug Authority's Decree 475/2025 established national track and trace deadlines under the Unified National Electronic System, with finished imported products subject to a February 1 2026 cutoff and bulk imported as well as locally manufactured, packaged, or repackaged products falling under an August 1 2026 deadline. In April 2026, the Authority issued Phase 1 Technical FAQ version 3.0, defining mandatory technical, data, serialization, aggregation, and reporting requirements, including DataMatrix codes, human-readable interpretation, and standardized reporting across the legal supply chain. These developments are already reshaping vendor engagements, seminar-driven capacity building, and localized solution design for manufacturers and third-party logistics providers operating in the region.
Why Probabilistic Forecasts Are Insufficient for Enterprise Planning
Many market summaries publish top-line numbers and leave strategic leaders to infer integration complexity, regional readiness, and vendor capability gaps on their own. Our report takes a different approach. Rather than providing a static snapshot, we decompose the revenue trajectory into the operational drivers that actually determine where budgets land in 2026: the pace at which serialization requirements move from pilot to full-line deployment, the degree to which aggregation becomes a mandatory layer for case and pallet visibility, and the extent to which software and services expansion offsets hardware procurement cycles. By anchoring analysis in these decision-grade dimensions, our research equips teams to build realistic scenario models instead of relying on headline CAGR figures alone.
Coding and Marking Systems and Solutions Market
Inside the Research: What Decision-Makers Will Find
Market Architecture and Revenue Trajectories
The report opens with a fully sourced historical reconstruction spanning 2020 through 2025 and extends the forecast through 2032. Readers gain a year-by-year view of how market revenue has evolved, the inflection points that reshaped demand, and the projected growth cadence that informs long-range investment decisions. All monetary values are expressed in USD millions, enabling direct integration with enterprise financial models and procurement planning workflows.
Component and Application Dynamics
We examine how the market is Split by components and applications, illuminating where capability requirements are intensifying. Hardware and software solutions each play distinct roles in implementation success, and the balance between them often dictates total cost of ownership, deployment timelines, and long-term scalability. Similarly, the application landscape—dominated by serialization but increasingly shaped by aggregation requirements and other operational layers—rewards detailed scrutiny. Organizations that understand these internal market mechanics are better positioned to align technology roadmaps with regulatory milestones rather than retroactive retrofitting.
Competitive Positioning and Vendor Ecosystem
The research profiles the companies actively shaping the competitive landscape and provides a structured lens for evaluating strategic fit, geographic reach, and technical differentiation. The ecosystem includes players with strong serialization, aggregation, and regulatory compliance platforms; cloud-native interoperability networks; full-stack solutions supporting multi-level standards with localized compliance for emerging markets and established jurisdictions; integrated manufacturing execution systems with embedded track-and-trace capabilities; and specialized hardware, software, mobility, printing, and data capture technologies that enable real-time serialization and verification across supply chain touchpoints. We also cover providers focused on Level 1 and Level 2 serialization platforms for manufacturing authenticity and compliance, B2B integration and compliance solutions for pharmaceutical data exchange, complete Level 0-4 serialization and aggregation offerings for pharmaceutical companies, contract manufacturers, and OEMs, machine and software solutions for packaging lines, packaging and serialization equipment with integrated track-and-trace capabilities, and dedicated track-and-trace and serialization platforms for pharmaceutical supply chains. Understanding where each organization competes—and where capability gaps remain—allows buyers and investors to make more informed partnership, procurement, and market-entry decisions.
Several recent developments underscore how rapidly the field is moving. In early 2026, an exclusive partnership was announced to deliver localized end-to-end serialization and aggregation solutions for Egyptian pharmaceutical manufacturers and third-party logistics providers, directly targeting enforcement deadlines for the Egyptian regulatory framework. Around the same period, a strategic commercial partnership was formed to integrate AI-powered production planning with traceability operations for pharmaceutical manufacturers, signaling a broader shift toward linking operational planning with compliance workflows. Meanwhile, industry events have increasingly focused on supply chain traceability benchmarks and practical implementation guidance aligned with national track and trace requirements and GS1 standards, reflecting growing demand for hands-on deployment knowledge rather than high-level regulatory overviews.
Market Structure and Concentration Insights
Beyond vendor profiles, the report examines market concentration to help readers understand where competitive pressure is most intense and where niche or regional specialization may still create value. By analyzing concentration metrics, the research enables procurement teams to evaluate supplier risk, negotiate from a more informed stance, and identify scenarios where consolidation or multi-vendor strategies may be warranted.
Translating Market Intelligence Into 2026 Strategy
The most valuable use of this research is not simply to confirm that the market is growing, but to determine how your organization should respond. PW Consulting's analysis is designed to support several concrete decision pathways:
- Technology roadmapping. Align serialization, aggregation, and verification investments with the precise regulatory milestones that affect your markets, rather than building generic capability that may not meet local data, reporting, or interoperability requirements.
- Vendor selection and consolidation. Use structured competitive analysis to differentiate between providers offering true end-to-end interoperability and those delivering point solutions that may create integration debt as compliance requirements expand.
- Regional readiness planning. Anticipate where new technical FAQs, enforcement phases, and localized compliance requirements will create time-sensitive deployment needs, particularly in markets where national track and trace systems are moving from policy to active implementation.
- Financial scenario modeling. Incorporate the full historical-and-forecast revenue path, component and application dynamics, and market concentration patterns into multi-year budgeting rather than relying on static point estimates.
For executives who must justify capital allocation in 2026, the question is no longer whether track and trace capabilities matter. The question is whether the organization's deployment model is sufficiently integrated, scalable, and regionally aware to meet simultaneous obligations across multiple regulatory architectures. Our report provides the evidence base needed to answer that question with confidence.
A Preview of What Lies Ahead
This article offers only a high-level view of the strategic terrain. The complete PW Consulting Pharma Track and Trace Solutions Market research goes much further, delivering detailed historical reconstruction, multi-year forecasts, component and application analysis, competitive profiles, recent partnership and regulatory developments, and concentration insights that can be immediately embedded into board-level planning, procurement negotiations, and market-entry assessments.
For teams preparing for 2026 decisions—whether they are evaluating serialization platforms, aggregation requirements, cloud-based traceability networks, manufacturing execution integration, or localized compliance deployments for emerging regulatory markets—the full report provides the depth required to move from reactive compliance to proactive strategic advantage. Readers seeking the complete dataset, full segmentation analysis, and detailed competitor profiles are invited to access the full market research on the PW Consulting portal, where the full intelligence package is available for download and executive review.
In a market moving at this pace, the organizations that win will be those that treat traceability not as a compliance footnote, but as a structured, data-driven investment domain. Our research is built to help you make that case with clarity, precision, and decision-grade confidence.
For detailed analysis of this topic, please visit the official page: Pharma Track and Trace Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PVDF Market Hits $1.37B in 2025, Surging to $2.48B by 2032 on 8.8% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Polyvinylidene Difluoride Market 2026-2032
As global industries navigate a period of rapid technological transition, supply chain recalibration, and evolving regulatory landscapes, Polyvinylidene Difluoride (PVDF) has emerged as a critical enabler across energy storage, advanced chemical processing, and high-performance filtration. For executives, supply chain leaders, and R&D directors, understanding where this market is headed is no longer optional—it is foundational to capital allocation, capacity planning, and competitive positioning. Our latest comprehensive research delivers the strategic intelligence required to make informed decisions in 2026 and beyond.
Over the past half-decade, the PVDF sector has demonstrated remarkable momentum, driven by expanding demand from lithium-ion battery manufacturing, next-generation water treatment infrastructure, and specialized high-purity coatings. Historical trajectory data reveals a clear upward arc: the market generated approximately 800 million USD in 2020, gradually climbed past the 920 million USD threshold in 2022, crossed the 1,200 million USD milestone by 2024, and reached an estimated 1,372 million USD by 2025. This established baseline sets the stage for what analysts project will be a sustained growth phase. Looking ahead to the 2026-2032 forecast window, the market is expected to scale from roughly 1,497 million USD in 2026 toward nearly 2,479 million USD by the close of the decade. This trajectory translates to a compound annual growth rate of 8.8 percent, positioning PVDF as one of the most structurally resilient specialty polymer segments in the broader advanced materials landscape.
For enterprise leaders, these figures are more than retrospective benchmarks—they are strategic signals. An accelerating growth rate of this magnitude implies tightening supply-demand balances, heightened competition for qualified raw material streams, and an urgent need to secure reliable downstream partnerships before capacity constraints or pricing volatility erode margins. Companies that approach 2026 without a clear view of regional demand nodes, application-specific consumption patterns, and evolving cost structures risk reactive decision-making in a market that rewards foresight.
Decoding the Operating Environment: Dynamics Shaping 2026
No market strategy is complete without a granular understanding of the operational forces currently reshaping PVDF supply chains. Several intersecting dynamics are already influencing production economics and demand trajectories, and their cumulative impact will define competitive outcomes throughout the forecast period.
On the raw material front, the sector has faced notable supply pressure. A pronounced shortage of hydrogen fluoride during the second quarter of 2025 forced approximately ten percent production cuts across several Chinese PVDF plants, triggering a rapid elevation in global spot prices. Compounding this vulnerability is the broader chemical input environment: a twelve-fold surge in R-142B pricing between 2023 and 2024 pushed PVDF production costs upward by 18 to 25 percent, disproportionately squeezing smaller manufacturers with thinner balance sheets. Adding another layer of structural complexity, China currently controls over three-quarters of global VDF production capacity. Recent environmental clampdowns in Jiangsu and Shandong provinces have already driven 10 to 12 percent cost spikes on a quarter-on-quarter basis, underscoring how tightly coupled regional compliance enforcement is with global cost curves.
Simultaneously, regulatory evolution is introducing profound uncertainty and opportunity. Europe has moved closer to a potential blanket restriction on PVDF membranes following an updated dossier from the European Chemicals Agency (ECHA) that explores banning the manufacture of all per- and polyfluoroalkyl (PFAS) substances. While the final scope and timeline remain under active review, the mere trajectory of this regulatory conversation is already prompting downstream adopters to re-evaluate supplier diversification, material substitution pathways, and long-term procurement commitments. In markets where compliance timelines intersect with capital-intensive production cycles, anticipating regulatory inflection points is a decisive competitive advantage.
The strategic takeaway is clear: cost volatility, regional capacity concentration, and evolving chemical regulations are not peripheral concerns. They are central to pricing strategy, supplier negotiations, and geographical expansion planning. Companies that map these dynamics to their specific operational footprints will be positioned to manage risk proactively rather than react to margin compression after the fact.
Polyvinylidene Fluoride (PVDF) (PVDF Resin) Market
Mapping Competitive Forces and Industry Structure
The PVDF market exhibits a moderately concentrated competitive structure, with the top three players collectively commanding approximately 55 percent of market share and the leading five firms extending their combined presence to roughly 65 percent. This concentration pattern reflects decades of technical specialization, established fluoropolymer processing expertise, and long-term relationships with high-specification end users. Yet the landscape is far from static. The remaining market share is distributed across a mix of regional specialists, application-focused innovators, and emerging capacity builders, all of whom are actively carving out positions through targeted product development and strategic manufacturing investments.
Several established multinational and regional players define the current industry architecture. Arkema S.A., headquartered in Colombes, France, has been actively strengthening its PVDF footprint, most notably through its Kynar brand. In March 2026, Arkema announced a 20 percent capacity expansion at its Changshu site in China, with startup scheduled for 2028. This expansion is explicitly designed to support surging demand across lithium-ion batteries, energy storage systems, high-performance coatings, chemical processing, semiconductors, water filtration, and wire and cable applications. Solvay S.A., based in Brussels, Belgium, maintains a differentiated position through its advanced specialty polymer portfolio, leveraging deep formulation expertise and global technical service networks. Kureha Corporation, situated in Tokyo, Japan, brings longstanding fluoropolymer engineering heritage and a strong presence in high-purity industrial applications. Daikin Industries, Ltd., also headquartered in Osaka, Japan, continues to invest in fluorine chemistry capabilities that underpin high-performance membrane and coating solutions. In China, Shanghai Huayi 3F New Materials Co., Ltd. and Shanghai Ofluorine Chemical Technology Co., Ltd. represent rapidly scaling domestic players that are expanding their technical portfolios and aligning closely with regional demand surges, particularly in energy storage and industrial processing. Rounding out the competitive set, 3M Company, based in St. Paul, Minnesota, United States, applies its broad materials science platform to specialized PVDF-enabled solutions across filtration, electronics, and industrial coatings.
Recent corporate activity underscores how aggressively incumbents are positioning for the next demand cycle. Capacity additions, formulation upgrades, and regional manufacturing investments are no longer isolated R&D projects—they are strategic infrastructure plays designed to lock in supply preference with high-growth end markets. Understanding the timing, scale, and geographic focus of these moves is essential for any organization evaluating partnership opportunities, assessing competitive exposure, or planning its own capacity strategy.
Inside the Research: What Decision-Makers Will Find
A market report of this scope must do more than chart growth curves. It must translate macro trends into operational intelligence that can be actioned across procurement, product development, sales strategy, and investment planning. Our analysis is structured to deliver precisely that bridge between high-level market intelligence and day-to-day strategic execution.
The research framework begins with a robust historical reconstruction spanning 2020 through 2025, establishing baseline consumption patterns, pricing behavior, and demand composition before projecting forward across the 2026-2032 window. From there, the analysis segments the market across multiple structural dimensions, allowing readers to isolate the specific demand drivers, application growth rates, and product-type dynamics that matter most to their business models. Rather than presenting a single aggregate number, the report unpacks how different segments reinforce or diverge from the overall growth trajectory, enabling executives to identify where capital deployment will yield the strongest returns and where latent demand risks may be underestimated.
Beyond segmentation, the publication delivers a comprehensive competitive mapping exercise. It profiles the operating strategies of key market participants, evaluates recent capacity and investment announcements, and contextualizes each player’s positioning relative to regional demand centers and technical differentiation. This competitive layer is paired with a supply chain and cost structure assessment that traces input dependencies, highlights vulnerability nodes, and identifies where margin pressure is most acute. Given the raw material sensitivity documented in recent quarters, this dimension alone can materially improve procurement negotiation leverage and inventory planning accuracy.
The regulatory and compliance landscape receives dedicated analytical treatment as well. With evolving chemical governance frameworks intersecting with long-lived infrastructure and capital equipment decisions, the report maps potential policy trajectories, evaluates downstream substitution feasibility, and outlines strategic response pathways. For organizations operating in or selling into European markets, or for those dependent on PVDF-enabled membranes and coatings in regulated environments, this section provides a structured view of compliance risk rather than speculative headlines.
Finally, the research integrates demand-side application intelligence across energy storage, industrial piping and fittings, advanced coatings and membranes, and other high-value use cases. By connecting application growth signals to regional manufacturing footprints, raw material availability, and competitor capacity timelines, the report equips strategy teams to answer a far more valuable question than market size alone: which opportunities are defensible, which are commoditizing, and where should resources be concentrated in 2026 and the years immediately following?
Polyvinylidene Difluoride (PVDF) Market
Turning Market Intelligence into 2026 Competitive Advantage
The strategic value of this research lies in its ability to convert complex, fast-moving market signals into a coherent decision-making framework. In a segment where capacity expansions are being announced years in advance, where raw material cost spikes can compress margins within a single quarter, and where regulatory trajectories can reshape demand assumptions overnight, reactive planning is a structural disadvantage. Organizations that ground their 2026 strategies in verified market sizing, segmentation clarity, competitive intelligence, and dynamic supply chain analysis will enter the forecast period with significantly greater operational confidence.
For procurement leaders, the analysis highlights where long-term contracting, alternate sourcing architectures, and cost-indexing mechanisms can mitigate volatility exposure. For product and R&D teams, it clarifies which application domains are scaling fastest and which technical specifications are becoming table stakes versus differentiators. For commercial and corporate strategy functions, it surfaces where competitive concentration creates partnership opportunities, where regional demand imbalances may justify localized investments, and where regulatory developments may accelerate or decelerate adoption curves. In each case, the underlying market intelligence serves as a shared reference point, reducing internal disagreement and accelerating execution.
Access the Complete Strategic Analysis
The overview presented here reflects the analytical framework, directional market signals, and structural dynamics that define the current PVDF landscape. It is designed to establish the strategic context and demonstrate the depth of insight available to decision-makers who require more than headline figures. However, the full segmentation breakdowns, region-specific demand mapping, product-type growth trajectories, application-level consumption analysis, and detailed competitive profiles are reserved for the complete market research publication.
For organizations preparing capital allocation decisions, supplier negotiations, capacity evaluations, or market entry assessments in 2026, the complete dataset provides the precision necessary to move from directional confidence to executable strategy. We invite you to access the full report to obtain the comprehensive intelligence, granular segmentation detail, and forward-looking scenario analysis required to navigate the next phase of PVDF market evolution with clarity and strategic conviction.
For detailed analysis of this topic, please visit the official page: Polyvinylidene Difluoride (PVDF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global automatic storage system market is projected to grow consistently from 2020 to 2035, reflecting compound annual growth driven by automation demand in warehousing, retail, and manufacturing. Revenue is estimated at $7,500 million in 2025, surging past $19,300 million by 2035. Significant inflection points are anticipated in 2027 and 2031, corresponding to large digital initiatives and the accelerated rollout of cloud-connected AS/RS offerings. Major sectors including e-commerce, automotive, and food & beverage are expected to account for much of this growth trajectory.
Read More - https://bussinessinsights.com/research-report/global-automatic-storage-system
By application, the automotive sector retains the largest market share in the automatic storage system market for 2025, supported by ongoing investments in smart factories and lean manufacturing. E-commerce and retail closely follow, propelled by the need for speed and accuracy in online order fulfillment. The food & beverage and healthcare industries exhibit fast-growing adoption rates as regulatory compliance and cold storage efficiency become business imperatives. Aerospace and other sectors maintain steady growth, driven by the need for high-accuracy parts storage and rapid inventory agility.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-automatic-storage-system
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Warehouse Robotics Market to Hit $19.3B by 2032, 16.8% CAGR
By PW Consulting, 2026-09-16
Navigating the Warehouse Robotics Revolution: Strategic Intelligence for 2026 Decision-Makers
The warehouse robotics market is entering a decisive inflection point. As businesses confront escalating labor constraints, volatile consumer demand, and the operational imperative of round-the-clock fulfillment, automation has transitioned from experimental pilot programs to core infrastructure. Our newly released Warehouse Robotics Market research provides a rigorous, forward-looking assessment of this transformation, delivering the analytical granularity required for capital allocation, vendor evaluation, and long-term operational strategy. Set against a historical baseline spanning 2020 through 2025 and a comprehensive forecast window extending to 2032, this report equips executives with the macro and micro intelligence needed to navigate a rapidly consolidating ecosystem.
Market Trajectory: From Acceleration to Structured Growth
Over the past half-decade, the warehouse robotics sector has demonstrated a pattern of accelerated investment punctuated by brief normalization cycles. Historical revenue expansion between 2020 and 2025 reflects widespread adoption across e-commerce, third-party logistics, and heavy distribution networks. Following a period of market recalibration in the mid-2020s, momentum has firmly reasserted itself. The forecast period from 2026 through 2032 projects sustained expansion, with the market advancing from a baseline of 7,543.03 million USD in 2026 toward 19,305.49 million USD by the terminal forecast year. This trajectory translates to a compound annual growth rate of 16.8 percent, signaling that robotics-driven throughput is no longer a niche advantage but a baseline expectation for competitive fulfillment operations.
These figures are not abstract indicators. They represent a structural shift in how warehouses are designed, staffed, and scaled. Facilities that previously relied on manual picking and fixed conveyor pathways are now reconfiguring floor layouts around flexible automation nodes. The recurring investment pattern visible in the historical series underscores that buyers are moving past one-off deployments and toward phased, integrated automation architectures. For executives planning budget cycles in 2026, understanding the velocity and persistence of this growth curve is essential to aligning procurement timelines with real demand signals rather than speculative bottlenecks.
What the Report Delivers: Actionable Architecture for Strategy Teams
This research is structured to move beyond surface-level sizing and into the operational mechanics that determine deployment success. Rather than presenting a single aggregated figure, the analysis dissects the market across technology categories, functional applications, and geographic demand patterns. Decision-makers will find clearly mapped pathways linking each segment to specific operational outcomes, procurement considerations, and integration constraints.
- Technology and form-factor evaluation that distinguishes between established automated guided vehicle architectures and the rapidly scaling autonomous mobile robot segment, including guidance on where each solution class delivers the strongest return under different throughput and zoning requirements.
- Application-level breakdowns spanning transportation, picking and placing, palletizing and depalletizing, and packing, with analytical commentary on workflow integration, cycle-time implications, and the operational trade-offs that dictate segment prioritization.
- Regional demand mapping that contextualizes where investment intensity is concentrating, enabling supply chain leaders to align facility rollouts, vendor sourcing, and localized support strategies with prevailing deployment momentum.
- Concentration and competitive benchmarks that clarify market share dynamics among leading integrators and platform providers, helping procurement teams assess vendor dependency risk, partnership leverage, and long-term technology roadmaps.
Beyond structural segmentation, the report integrates technology roadmaps, deployment maturity curves, and total cost of ownership considerations. Readers will gain a working framework for evaluating whether a given automation topology aligns with their facility footprint, SKU complexity, peak-season volatility, and labor availability. This is not a static catalog of solutions; it is an analytical instrument designed to support scenario planning, vendor shortlisting, and capital sequencing.
Competitive Landscape: Platform Differentiation in a Consolidating Market
The vendor environment has matured into a spectrum of highly specialized platforms, each pursuing distinct architectural philosophies and target workflows. Several organizations have emerged as defining players whose technology choices are actively shaping procurement standards and deployment expectations.
Warehouse Robotics Market
Symbotic has built its market position around AI-powered end-to-end warehouse automation, coupling high-density storage, automated picking, and palletizing within a proprietary robotics ecosystem. Its emphasis on integrated workflow orchestration appeals to operators seeking to compress multiple manual stages into a single coordinated system. Locus Robotics, by contrast, has advanced a robots-to-goods fulfillment model anchored in AI-driven autonomous mobile robots and fully autonomous array configurations, targeting facilities that prioritize scalable, human-collaborative picking workflows.
Worldwide Warehouse Robots Market
Geek+ continues to expand its footprint with AMR-based warehouse robotics, robot arm picking stations, high-speed mobile platforms, and embodied intelligence frameworks purpose-built for e-commerce and B2B fulfillment. AutoStore differentiates through energy-efficient autonomous robotics designed for high-density storage and order fulfillment across retail, healthcare, and third-party logistics environments, where space optimization and retrieval speed are paramount. Addverb provides a broad automation toolkit spanning autonomous mobile robots, AS/RS systems, and integrated picking and packing solutions, positioning itself as a flexible partner for diverse distribution center configurations.
Vecna Robotics focuses on autonomous mobile robots engineered for horizontal transport, lifting, and conveying within human-centric warehouse layouts, making its technology particularly relevant for mixed-inventory facilities that must preserve operator interaction while increasing material movement efficiency. ForwardX Robotics brings autonomous forklifts and AMRs to warehouse and manufacturing material handling, addressing environments where heavy-load mobility and structured aisle navigation are critical. Ocado has built recognition around its On-Grid Robotic Pick technology and end-to-end fulfillment automation systems, emphasizing precision picking and scalable grocery and consumer goods operations. Exotec rounds out the landscape with Skypod AS/RS systems that integrate autonomous robotics for high-density, high-performance storage and retrieval.
These companies are not merely competing on hardware specifications. Recent product and deployment activity illustrates how quickly the competitive frontier is shifting. In early 2026, Locus Robotics introduced a fully autonomous Locus Array robots-to-goods fulfillment system that combines mobile robotics, integrated picking arms, and AI perception to support end-to-end workflows with reduced manual intervention. In the same period, Addverb unveiled the Trakr 2.0 high-order carousel automation system alongside three new warehouse robots and the Brisk interface at LogiMAT India 2026, signaling increased emphasis on storage automation and operational safety. Geek+ also introduced a robot arm picking station marketed as an end-to-end unmanned picking solution, along with an embodied intelligence platform aimed at expanding adaptive manipulation capabilities. Separately, Symbotic marked a significant deployment milestone by reaching one million robots deployed across fulfillment centers worldwide, reinforcing the scale at which AI-powered robotic warehouse systems are now operating.
For buyers, this level of activity carries both opportunity and risk. Differentiation is accelerating, but integration complexity, interoperability standards, and vendor roadmap stability are becoming equally important evaluation criteria. The report contextualizes these competitive movements so that procurement and operations leaders can assess not just what a vendor offers today, but how its trajectory aligns with a facility’s multi-year automation plan.
Industry Dynamics Shaping 2026 Procurement and Deployment
Technology capability is only part of the deployment equation. External cost pressures, regulatory evolution, and infrastructure considerations are actively reshaping project economics and timing. In 2025, rising steel and aluminum costs driven by tariff exposure increased the price of warehouse automation projects, compressing budget headroom for some operators and forcing trade-offs between scope and staging. By 2026, procurement teams are responding with more modular deployment strategies, phased capital releases, and stronger emphasis on lifecycle cost modeling rather than upfront price comparisons alone.
Regulatory and safety frameworks are also evolving in ways that influence system design and acceptance testing. The 2025 revision of ISO 10218-1 introduced technical changes reflecting marketplace developments and updated risk mitigation requirements for industrial robots, prompting engineering teams to revisit safeguarding architectures and integration protocols. At the same time, OSHA continues to operate without robotics-specific standards, instead requiring employers to eliminate recognized hazards under the General Duty Clause, which places a premium on site-specific risk assessments and documented safety processes. Fire protection guidance adds another layer of complexity: NFPA 13 sprinkler protection requirements for AS/RS systems remain under review because manufacturer-specific configurations in automated storage and retrieval create variability in hazard modeling and suppression planning.
Trade policy and regional industrial strategy are introducing further uncertainty. The EU industrial strategy and import tariffs on robotics components may raise short-term prices while simultaneously encouraging regional manufacturing and localized supply chains. For multinational operators, this means vendor selection cannot be reduced to performance specifications alone; sourcing geography, parts availability, service coverage, and tariff exposure now sit squarely within the strategic evaluation matrix.
Why This Research Matters for 2026 Strategy
The convergence of strong market growth, rapid product innovation, and shifting cost and regulatory conditions makes 2026 a pivotal planning year. Companies that treat warehouse robotics as a tactical purchase risk under-scoping integration requirements, overestimating deployment readiness, or locking into platforms that lack the scalability needed for future volume spikes. Companies that approach robotics through a structured intelligence framework can sequence investments more efficiently, match technology to workflow reality, and build vendor relationships around transparent performance expectations.
Our report is designed to support that decision-making process at multiple levels. Executive teams can use the market trajectory and concentration analysis to frame capital planning and risk posture. Operations leaders can leverage the segmentation and application analysis to prioritize automation nodes that deliver the fastest operational leverage. Procurement and engineering groups can draw on the competitive and regulatory context to refine vendor scorecards, integration checklists, and safety validation workflows.
The full dataset, segment-level modeling, vendor evaluation frameworks, and deployment scenario analysis are available in the complete report. For organizations preparing multi-quarter automation roadmaps or evaluating major systemintegrations in 2026, the detailed findings provide the evidentiary base needed to move from preliminary interest to confidently structured investment.
For detailed analysis of this topic, please visit the official page: Warehouse Robotics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Diabetes Drugs Market to Hit $117.7B by 2032, 6.5% CAGR Amid GLP-1 Growth
By PW Consulting, 2026-09-16
# The Diabetes Drugs Market in 2026: Navigating Growth, Innovation, and Strategic Complexity ## Executive Summary: Why Deep Intelligence Matters Now The global landscape for diabetes management is undergoing a seismic shift, driven by breakthrough therapies, evolving reimbursement models, and persistent supply chain vulnerabilities. For executives, investors, and strategic planners, relying on surface-level data is no longer sufficient. The decisions made in 2026 will dictate competitive positioning for the remainder of the decade. This article provides a high-level strategic overview of the market environment, illustrating the complexity and opportunity that define the sector today. However, true strategic advantage requires granular precision that goes beyond public headlines. Our comprehensive Diabetes Drugs Market research report delivers the specific segmentation volumes, competitive share analysis, and future trajectories necessary to optimize your portfolio and entry strategies. ## Market Trajectory and Scale: A Decade of Expansion The diabetes drugs market has demonstrated consistent resilience and growth over the past half-decade, establishing a robust foundation for the forecast period extending through 2032. Between 2020 and 2025, the market experienced significant expansion, with revenues rising from 51.0 billion USD to 75.9 billion USD. This historical performance underscores the inelastic demand for chronic care solutions and the rapid adoption of newer therapeutic classes. Looking forward, the market is projected to sustain a Compound Annual Growth Rate (CAGR) of 6.5 percent during the 2026 to 2032 forecast period. This trajectory suggests that the market will surpass the 100 billion USD milestone shortly after the turn of the decade, reaching approximately 117.7 billion USD by 2032. Such growth is not uniform; it is fueled by specific innovation waves and regional dynamics that require careful unpacking. While the top-line figures indicate a healthy sector, the distribution of this growth across drug classes, diabetes types, and geographic regions reveals critical niches where value is being created and captured. Understanding where the revenue streams are concentrating is vital for resource allocation, yet these specific breakdowns are detailed within our full proprietary dataset. ## The Innovation Engine: Drug Classes and Therapeutic Shifts The competitive battlefield is defined by the performance of distinct drug classes, each carrying different risk profiles, pricing power, and patient adherence rates. The market has seen a pronounced pivot toward incretin-based therapies, which have reshaped expectations for glycemic control and weight management. Conversely, traditional insulin markets remain foundational but face pressure from biosimilar competition and novel delivery mechanisms. Recent regulatory milestones highlight the pace of innovation. In March 2026, Novo Nordisk received FDA approval for Awiqli (insulin icodec-abae), a once-weekly insulin designed to improve glycemic control for type 2 diabetes. This approval represents a significant advancement in patient convenience and potentially adherence, disrupting the daily injection paradigm. Alongside such developments, the market landscape is being reshaped by key industry players who are leveraging distinct portfolios to capture share. Our report provides an in-depth profiling of the entities driving these changes. Leading manufacturers such as Novo Nordisk A/S, headquartered in Bagsværd, Denmark, continue to dominate with a strong lineup including Ozempic, Wegovy, and Rybelsus. Their strategy focuses heavily on the intersection of diabetes and obesity management. Similarly, Eli Lilly and Company, based in Indianapolis, Indiana, USA, is pushing the envelope with GLP-1 and GIP receptor agonists, including Mounjaro, Zepbound, and the investigational orforglipron, targeting both glycemic control and obesity-related metrics. Traditional insulin leaders remain relevant through formulation innovation. Sanofi, headquartered in Paris, France, maintains a strong presence with long-acting insulins like Lantus and Toujeo. Meanwhile, the SGLT2 inhibitor space is contested by developers like Boehringer Ingelheim, based in Ingelheim am Rhein, Germany, with products such as Jardiance, and Janssen Pharmaceuticals, located in Beerse, Belgium, offering Invokana for type 2 diabetes management. The interplay between these giants involves patent cliffs, pipeline Succession, and strategic partnerships that are meticulously analyzed in our full report to help you anticipate market share shifts. ## Geography and Patient Segmentation: Where the Revenue Lies Revenue distribution is not homogeneous across the globe. Certain regions exhibit higher purchasing power and faster adoption rates for premium therapies, while others offer volume growth potential driven by prevalence rates and improving healthcare infrastructure. The concentration of value in specific geographic zones creates distinct regulatory and pricing challenges for multinational strategies. Similarly, the patient base is segmented by diabetes type, with the vast majority of therapeutic spend directed toward Type 2 diabetes management, reflecting the global burden of metabolic syndrome. Type 1 diabetes, while smaller in terms of total revenue volume, represents a critical area for innovation in insulin delivery and immunosuppression therapies. The nuances of how these segments interact with drug class preferences—for instance, the preference for SGLT2 inhibitors in specific comorbidity profiles versus insulin dependence in advanced cases—require detailed modeling. Our research breaks down these segments to identify high-growth pockets that are often obscured in aggregate market figures. Access to the full segmentation data allows stakeholders to pinpoint exactly where their products fit within the current hierarchy of treatment guidelines. ## Market Concentration and Competitive Intensity The diabetes drugs market is characterized by a moderate level of concentration, suggesting room for niche players while maintaining strong barriers to entry for complex biologics and patented formulations. The top three companies hold a significant portion of the market share, collectively accounting for approximately 50 percent of revenue. Expanding the view to the top five players, the concentration rises to 65 percent. This structure indicates a market dominated by well-capitalized incumbents with extensive distribution networks and regulatory expertise. However, concentration does not imply stagnation. The remaining 35 percent of the market is highly competitive, with opportunities arising from generic entry, biosimilar development, and novel mechanisms of action. Strategic decisions regarding M&A, licensing, or organic pipeline development must account for this concentration risk. Entering a market segment dominated by the top five requires a differentiated value proposition, whether through superior clinical outcomes, cost efficiency, or delivery convenience. Our competitive landscape analysis dives deeper into the strategic moves of these key players, evaluating their R&D pipelines, litigation status, and global expansion strategies to provide a clear picture of the barriers and opportunities ahead. ## Supply Chain and Regulatory Dynamics: Navigating Risk in 2026 Beyond the clinical data and revenue projections, the operational environment for diabetes drugs is fraught with logistical and regulatory complexities. Supply chain resilience has emerged as a critical strategic pillar, particularly concerning the sourcing of key starting materials and active pharmaceutical ingredients (APIs). Recent analysis by the United States Pharmacopeia (USP) highlights a significant vulnerability: nearly half (48 percent) of key starting materials for drugs on the USP vulnerable medicines list are solely manufactured in a single country. This concentration poses acute and chronic risks to the supply of diabetes medications should disruptions occur. Furthermore, the USP emphasizes that upstream starting material sourcing bottlenecks could impact the availability of essential medicines. In the context of raw materials, 48 percent of global API Drug Master Files (DMFs) originate from India. This heavy reliance underscores the need for diversified sourcing strategies and robust contingency planning. Regulatory and reimbursement landscapes are also shifting dynamically. The Centers for Medicare & Medicaid Services (CMS) has introduced the GLP-1 Bridge model, providing access at a $50 copay for eligible Medicare beneficiaries with standardized coverage criteria. Additionally, the Medicare GLP-1 Bridge program offers eligible Part D beneficiaries $50 monthly access to certain GLP-1 medications beginning July 1, 2026. These initiatives are designed to improve patient access but introduce new variables for pricing strategy and demand forecasting. Stakeholders must understand how these reimbursement changes affect volume projections and manufacturer rebates. Our report synthesizes these regulatory developments with market demand models to predict how policy shifts will alter consumption patterns and profitability across different payer segments. ## Strategic Implications for Industry Stakeholders The convergence of robust market growth, therapeutic innovation, and supply chain fragility creates a complex decision matrix for 2026. Manufacturers must balance the urgency of launching new formulations against the risk of supply disruptions. Investors need to discern which drug classes will sustain premium pricing versus those facing imminent generic erosion. Policymakers and payers are grappling with the cost implications of widespread GLP-1 adoption while trying to expand access. To navigate this environment, organizations require more than just top-line growth numbers. They need a granular understanding of how segmentation splits interact with regional regulations, how competitive concentration affects pricing power, and how supply chain dependencies impact product availability. The data provided in public summaries often lacks the depth required to model these scenarios accurately. For instance, knowing the overall market size is useful, but understanding the specific revenue contribution of SGLT2 inhibitors versus GLP-1 receptor agonists in North America versus Asia Pacific is essential for regional market entry or expansion plans. ## Conclusion: The Value of Granular Intelligence The diabetes drugs market is poised for significant expansion through 2032, driven by a CAGR of 6.5 percent and evolving therapeutic standards. However, realizing value in this market requires precise intelligence. The interplay between major pharmaceutical players, regional demand variations, drug class performance, and regulatory policies creates a landscape where general knowledge is insufficient for competitive advantage. Our comprehensive Diabetes Drugs Market research report goes beyond the macro trends to provide the detailed segmentation data, competitive profiles, and strategic analysis necessary for informed decision-making. By uncovering the specific revenue splits, concentration metrics, and dynamic risk factors, this report equips stakeholders to mitigate risk and capitalize on growth opportunities with confidence. We invite you to explore the full findings to gain the actionable insights needed to thrive in this evolving sector.
Diabetes Drugs Market
Fertility Drugs Market
For detailed analysis of this topic, please visit the official page: Diabetes Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global eco-friendly lifts market revenue is forecasted to reach USD 14,700 Million in 2025, up from USD 10,150 Million in 2021, as sustainable construction accelerates across regions. Annual revenue is projected to exhibit a steady CAGR of 6.2% during 2025-2035, driven by increasing demand for energy efficiency and regulatory compliance. The chart highlights a consistent upward trajectory, with revenue expected to surpass USD 27,450 Million by 2035 as green building mandates strengthen and eco-lift retrofitting gains traction in renovation and infrastructure upgrade projects globally.
Read More - https://bussinessinsights.com/research-report/global-eco-friendly-lifts
The commercial segment leads eco-friendly lift adoption in 2025, representing 40% of market share, as commercial developers focus on sustainable and energy-efficient building design to comply with green certifications. The residential segment follows closely with 33%, reflecting increasing awareness and demand for eco-friendly technologies in multifamily and high-rise housing. Healthcare and institutional applications make up 15% and 8% respectively, where reliability and operational efficiency are crucial. Industrial use and other segments collectively account for 4%. This breakdown highlights the sector’s prioritization of eco-friendly solutions for high-traffic environments and the growing integration in residential new builds and retrofits globally.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-eco-friendly-lifts
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global in-wheel motors market is anticipated to grow from $752 Million in 2025 to $3,486 Million by 2035, representing a compelling CAGR driven by mass adoption in EV fleets, commercial segments, and high-performance applications. Revenue surges post-2027 as regulatory mandates and cost reductions facilitate deeper market penetration. Continuous product improvements, OEM alliances, and diversification into new vehicle categories further underpin positive revenue outlook for the forecast period.
Read More - https://bussinessinsights.com/research-report/global-in-wheel-motors
Passenger vehicles dominate the in-wheel motors market in 2025, reflecting high-volume integration by major OEMs innovating electric vehicle platforms. Electric buses form a significant segment as urban public transport electrification accelerates in Asia and Europe, benefiting from in-wheel motors’ modularity. Electric two-wheelers, driven by urbanization and micro-mobility trends in developing nations, round out the top applications. The distribution underscores manufacturers' focus on mainstream mobility solutions and rapid deployment in emission-sensitive city transit systems.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-in-wheel-motors
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global top hammer drilling tools market is poised to grow from USD 3,820 Million in 2025 to approximately USD 6,950 Million by 2035. This trajectory reflects a compound annual growth rate (CAGR) of 6.2% during this period. Steady demand from mining, construction, and infrastructure uprades, alongside advancements in automation and eco-friendly technologies, are driving revenue expansion. Increased infrastructure spending in emerging economies and the shift towards sustainable drilling solutions further support this upward trend. Large-scale mineral extraction initiatives, especially in Asia-Pacific and Latin America, continue to be major revenue contributors.
Read More - https://bussinessinsights.com/research-report/global-top-hammer-drilling-tools
The mining segment commands the largest share of the top hammer drilling tools market in 2025, comprising 43% of global demand. Construction follows with a share of 32%, and quarrying stands at 12%. The predominance of mining is attributed to major mineral extraction and exploration activities across regions such as South America, Asia-Pacific, and parts of Africa. Construction’s significant market share comes from ongoing investments in infrastructure, commercial, and residential developments. Quarrying’s stable demand is driven by aggregate production and stone extraction needs. The increasing adoption of tunneling and oil & gas applications highlights the versatility and adaptability of top hammer tools in diverse operational environments. Companies continue to innovate with specialized products catering to the unique requirements of each segment.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-top-hammer-drilling-tools
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Food Refrigerated Warehousing Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
The global food refrigerated warehousing market was valued at USD 130,100 million in 2025 and is projected to grow to USD 315,800 million by 2035. The historical trend from 2020 to 2025 shows gradual market expansion due to increasing demands for cold storage and evolving food industry standards. The projected CAGR from 2025 to 2035 stands at approximately 9.1%, driven by rising perishable food demand, e-commerce growth, and investment in advanced warehousing technologies worldwide.
Read More - https://bussinessinsights.com/research-report/global-food-refrigerated-warehousing-
By application in 2025, Dairy & Frozen Desserts account for 28%, Meat for 23%, Fruits & Vegetables for 20%, Fish & Seafood 14%, Bakery & Confectionery 9%, and Ready-to-Eat Food 6%. Dairy and frozen desserts dominate due to strong demand for value-added perishables and broad distribution networks. Meat and produce follow, reflecting their perishable nature and extensive cold chain requirements. The market is witnessing notable traction in ready-to-eat and bakery segments as consumer preferences evolve.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-food-refrigerated-warehousing-
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Insulating Oil Market Hits $3.41B in 2025, To Reach $5.06B by 2032 at 5.8% CAGR
By PW Consulting, 2026-09-16
Insulating Oil Market Intelligence Report 2026: Strategic Insights for Power Infrastructure Decision-Makers
The global power transmission and distribution sector stands at a critical inflection point. As aging infrastructure demands modernization and sustainability mandates reshape procurement criteria, insulating oil remains the silent enabler of grid reliability. At PW Consulting, our latest Insulating Oil Market study delivers a comprehensive, data-driven roadmap for corporate strategists, procurement leaders, and engineering executives. This introduction outlines the strategic architecture of the report, highlights the key dynamics that will define the 2026-2032 horizon, and explains why timely, granular market intelligence is no longer optional but essential for competitive positioning.
Executive Overview: Market Trajectory and Strategic Relevance for 2026
Over the historical review window of 2020 through 2025, the insulating oil sector has demonstrated consistent expansion, reflecting steady capital expenditure in electrical infrastructure and a gradual shift toward higher-performance dielectric fluids. The market valuation has progressed from a baseline exceeding two and a half billion USD in 2020 to an estimated base-year valuation approaching three point five billion USD by 2025. This trajectory underscores both the growing electrification footprint across emerging economies and the intensifying maintenance and upgrade cycles in mature grids.
Looking ahead, the 2026-2032 forecast period projects a compound annual growth rate of 5.8 percent. By 2032, the estimated market size is projected to cross the five billion USD threshold. These figures are not merely statistical milestones; they signal structural shifts in fluid chemistry, supply chain diversification, and regulatory compliance pathways. For executives planning capacity investments, supplier negotiations, or product development pipelines, understanding the velocity and direction of this growth is fundamental to mitigating risk and capturing value. The upcoming report translates these macro trends into actionable intelligence, mapping growth pockets, identifying inflection technologies, and quantifying the cost-of-compliance variables that are reshaping procurement economics.
Market Segmentation and Regional Dynamics Decoded
The insulating oil ecosystem is defined by three critical segmentation axes: type, application, and geography. Each dimension carries distinct pricing dynamics, regulatory exposure, and growth profiles that require separate strategic treatment.
By fluid type, the market is anchored by conventional mineral oil formulations, which continue to command the largest share due to legacy infrastructure compatibility and established refining supply chains. Simultaneously, ester-based and silicone-based alternatives are gaining accelerated adoption, driven by heightened fire safety requirements, environmental mandates, and extended equipment lifecycle expectations. The strategic tension between incumbent cost advantages and next-generation performance premiums creates nuanced procurement decisions that demand granular levelized cost analysis.
From an application standpoint, power transformers represent the dominant consumption channel, reflecting their central role in voltage regulation, grid stability, and long-distance transmission. Switchgear, circuit breakers, and reactance assemblies constitute the secondary demand pillar, offering a more specialized but technically demanding application segment where dielectric strength, moisture tolerance, and oxidation stability are non-negotiable performance benchmarks.
Geographically, the market exhibits pronounced divergence. Asia Pacific leads in absolute consumption volume, fueled by rapid grid expansion, industrial electrification, and large-scale infrastructure programs. The North American market reflects a mature but steadily evolving landscape shaped by grid hardening initiatives and aging substation replacements. Europe presents a distinct regulatory-led transition, where sustainability criteria and end-of-life fluid management protocols are accelerating reformulation and recycling investments. Latin American and Middle East and Africa regions operate at lower absolute volumes but exhibit targeted growth pockets tied to specific transmission upgrades and localized industrial demand. The report contains detailed regional demand-to-supply gap analysis, logistics cost modeling, and localized compliance impact assessments that are critical for market entry or capacity allocation decisions.
Insulating Oil Market
Competitive Intelligence: Incumbent Leadership and Strategic Market Maneuvers
The insulating oil sector is characterized by a moderately concentrated competitive landscape. Top-tier players collectively command a substantial share of global production capacity, with the top three and top five firms representing a dominant proportion of the revenue base. This concentration creates a marketplace where scale economies, proprietary refining technologies, and established utility relationships serve as durable moats, while simultaneously leaving space for agile niche players and sustainability-focused innovators to capture differentiated positioning.
The report profiles the core competitive set shaping the market trajectory. Nynas AB, headquartered in Stockholm, continues to reinforce its leadership position in naphthenic transformer oils through the NYTRO brand portfolio, with recent strategic emphasis on bio-based and sustainability-aligned formulations. In May 2025, the company advanced this direction by introducing Nytro Bio 300X, a bio-based ester transformer oil that achieved IEC 62770 vegetable-based fluid classification, delivering dielectric breakdown strength at 800 V/mm and a flash point exceeding 300°C. This launch illustrates how incumbents are leveraging performance credibility to transition legacy customer bases toward eco-compatible alternatives.
APAR Industries Limited, based in Vadodara, India, has built its POWEROIL lineup across naphthenic, iso-paraffinic, and ester-based grades that align with international performance standards. By August 2025, the company secured FM approval for its eco-friendly ester-based natural and synthetic transformer oils, a certification milestone that strengthens its credibility in safety-sensitive procurement environments and opens new addressable segments for sustainable fluid specifications. Savita Oil Technologies Limited, operating from Mumbai with over sixty years of petroleum specialty product experience, remains a recognized producer of TRANSOL transformer oils and insulating fluids, maintaining a strong service orientation for power transmission clients across long operating cycles.
Transformer Oil Market
On the Western hemisphere side, Ergon, Inc. of Jackson, Mississippi, continues to supply dielectric fluids and specialty transformer oils with global distribution reach and rigorous testing infrastructure. In July 2025, the company opened its first Transformer Oil Technology Center in Merak, Indonesia, a strategic facility designed to strengthen quality control, analytical testing, and regional supply responsiveness amid intensifying global energy demand. Aevitas Inc., based in Ayr, Ontario, operates as a specialized supplier and distributor of mineral and silicone insulating oils, complementing its product portfolio with on-site service capabilities and flexible packaging solutions tailored to Canadian and North American transformer operators. Cargill, Incorporated, headquartered in Minneapolis, has intensified its focus on BiO+ FR3 natural ester insulating fluids, emphasizing fire safety and biodegradability. Throughout 2025, the company executed capacity expansion initiatives in the United States to align production capability with rising demand for biodegradable transformer fluid alternatives.
In emerging regional markets, GANELEC of Cape Town delivers IEC-compliant premium transformer oils across Super, High, Standard, and Special grades, supported by filtration services and technical assistance specifically oriented toward African market requirements. The report provides a deeper competitive scoring framework, evaluating each profiled company on manufacturing scale, product breadth, sustainability positioning, certification depth, regional service coverage, and recent strategic capital deployment.
Regulatory Pressures, Environmental Compliance, and Raw Material Volatility
The insulating oil market does not operate in a regulatory vacuum. The 2026 outlook is heavily shaped by overlapping compliance layers that affect formulation choices, supplier qualification, and whole-life cost accounting. In May 2025, the European Union updated its REACH regulation list of Substances of Very High Concern, incorporating certain mineral oil categories used in transformer applications. This update introduces new labeling and reporting obligations with a compliance horizon extending into 2027, compelling distributors, OEMs, and utility operators to reassess inventory strategies, documentation workflows, and substitution pathways.
Beyond Europe, environmental regulations governing the storage, handling, and disposal of used mineral transformer oil are progressively tightening across OECD markets. These evolving standards add compliance overhead and procedural complexity, increasing the relative attractiveness of fluids with reduced environmental persistence and improved end-of-life recoverability. At the same time, crude oil price volatility continues to exert significant influence over the cost structure of petroleum-derived insulating oils. Annual fluctuations approaching thirty percent have been observed, directly affecting pricing predictability for naphthenic and paraffinic variants and reinforcing the case for long-term supply agreements, hedging strategies, and fluid performance optimization that reduces total volume consumption over asset lifecycles.
These dynamics converge to create a decision environment where technical specifications, regulatory foresight, and cost modeling must be integrated rather than evaluated in isolation. The report includes dedicated sections on compliance time horizons, environmental restriction impact mapping, and raw material price sensitivity simulations designed to support scenario planning.
What the Full Report Delivers: Scope, Methodology, and Decision Utility
The PW Consulting Insulating Oil Market study is structured to move beyond surface-level trend description and into operationally actionable intelligence. The full report encompasses historical performance reconstruction for the 2020-2025 period, a forecast model spanning 2026 through 2032, and a multi-layered segmentation framework that enables scenario testing across fluid types, application categories, and regional demand environments.
Key deliverables include:
- A calibrated market size and growth trajectory analysis with sensitivity parameters that reflect regulatory adoption speed, utility capex pacing, and fluid substitution rates.
- Detailed segmentation breakdowns that isolate volume and value dispersion patterns without oversimplifying the strategic differences between mineral, ester, and silicone fluid pathways.
- Competitive landscape assessment covering market share architecture, strategic positioning, product differentiation, certification portfolios, and recent corporate developments across the principal global and regional players.
- Regional market dynamics covering demand drivers, infrastructure investment cycles, import-export logistics considerations, and local compliance burdens that shape opportunity sizing and entry conditions.
- Regulatory and environmental impact analysis that maps impending compliance deadlines, disposal and recycling cost trajectories, and substitution economics for decision-makers evaluating long-term supplier contracts.
- Supply chain and raw material exposure assessment that highlights crude oil linkage, refining margin sensitivity, and logistics cost variability, supporting procurement resilience planning.
- Strategic recommendations tailored for manufacturers, distributors, utility procurement teams, and engineering service providers seeking to align product roadmaps, pricing strategies, and market prioritization with observable demand signals.
The report methodology integrates primary market intelligence, supplier and end-user structural analysis, regulatory tracking, and validated secondary data triangulation. This approach is designed to produce a decision-ready output rather than a passive data collection, ensuring that executive readers can translate findings into investment prioritization, supplier qualification criteria, and regional expansion logic.
Why This Study Matters for 2026 Portfolio and Procurement Strategy
As insulation technologies evolve and environmental expectations harden, organizations that rely on fragmented or outdated market assumptions will face disproportionate exposure to pricing shocks, compliance delays, and specification misalignment. The insulating oil market in 2026 will reward players who can synthesize technical performance, regulatory foresight, and supply chain realism into a coherent commercial strategy. Whether the objective is to secure reliable feedstock access, evaluate entry into ester-based fluid segments, benchmark competitive positioning, or model regional demand growth against infrastructure investment cycles, the underlying data architecture must be robust and current.
The full PW Consulting report provides the analytical depth required to make those decisions with confidence. It connects macro growth signals to segment-specific opportunity sizing, aligns competitive observations with strategic moat analysis, and translates regulatory noise into compliance timelines and cost implications. Most importantly, it preserves the granularity that executive teams need to differentiate viable initiatives from generic assumptions.
To access the complete segmentation models, competitive scoring matrices, regional demand dynamics, and forward-looking scenario frameworks, visit the official PW Consulting Insulating Oil Market research landing page and download the full report. The strategic insights contained within are designed to support informed, timely decision-making throughout the 2026-2032 planning window.
For detailed analysis of this topic, please visit the official page: Insulating Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com